INVESTMENT PROPERTY FINANCING, EXPLAINED
Your next rental.
Let’s put its
income to work.
Explore DSCR financing built around a rental property’s income—with less personal-income paperwork and a clear-eyed look at the deal.
Have a property in mind? Start with a conversation.
Does the rent
support the payment?
Principal + interest + taxes + insurance + applicable HOA dues.
Rent is 112% of the entered housing expense.
Some DSCR loan programs consider ratios of 0.75 or higher. Many lenders and loan investors prefer 1.00–1.25 or higher, with stronger ratios potentially supporting better rates and terms. Minimums and pricing vary by program, credit, down payment, and reserves.
DSCR is a ratio, not a percentage. Below 1.00, qualifying rent does not fully cover the housing expense used in the calculation.
Illustration only—not a qualification decision. Your rent entry is an assumption, not an appraisal. Program calculations vary. This is not a profit estimate.
THE IDEA IS SIMPLE. THE DETAILS MATTER.
A rental property.
A payment.
A closer look.
DSCR stands for debt service coverage ratio. The property’s qualifying rental income is central to the conversation. You and the property still need to meet the program’s requirements.
Start with DSCR basics ↗Review the rent.
What income can the lender actually use? Lease information and market-rent analysis can matter.
Review the payment.
Include the housing expenses the program requires—not just principal and interest.
Review the whole deal.
Discuss the property, credit, cash needed, reserves, and loan terms before making assumptions.
THE APPRAISAL HAS MORE THAN ONE IMPORTANT NUMBER
The price works.
But does the rent?
A strong value conclusion doesn’t automatically settle rental-income qualification. The rent accepted for underwriting can change the outcome.
Why the rent estimate deserves your attention ↗ILLUSTRATIVE SCENARIO · SAME $2,500 MONTHLY HOUSING EXPENSE
A $400 rent difference changes the ratio. Eligibility and available terms depend on the selected program; neither figure is an approval or denial.
A LIGHTER PERSONAL-INCOME PAPER TRAIL
Less paperwork.
More focus on
the property.
Typically, there’s no traditional personal-income qualification through W-2s, pay stubs, or tax returns. We’ll explain the documentation your particular transaction needs.
See what to have ready ↗WHAT MAY STILL BE NEEDED
01 Identification & application
02 Funds for closing & required reserves
03 Property, lease & insurance information
04 Credit, appraisal & title review
05 Entity documents, if applicable
Ask for your program-specific checklist.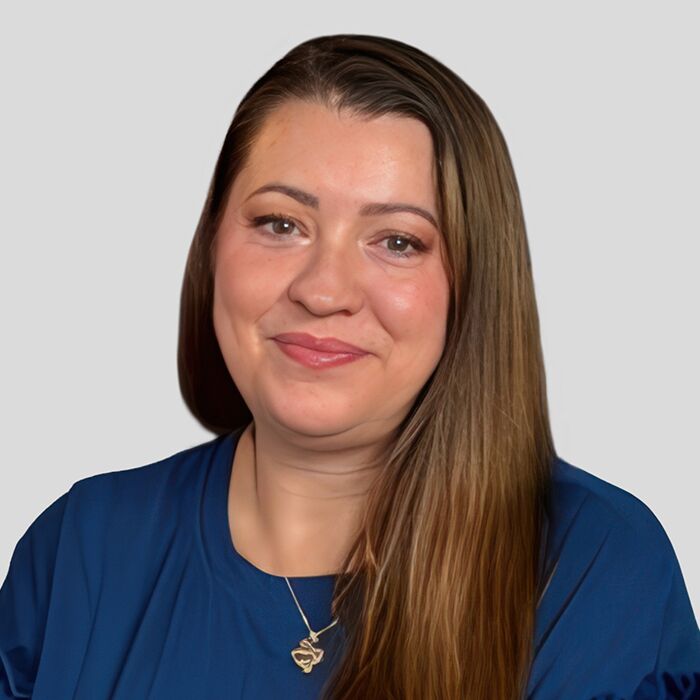
MEET YOUR MORTGAGE ADVISOR
Erika Slayton
Mortgage Advisor, Sr VP Mortgage Lending
With 30 years in mortgages, I bring a seasoned perspective and a candid conversation to your financing questions. Let’s look at your numbers, talk through the details, and identify the next step.
Let’s talk through your investment ↗THE INVESTOR READING ROOM
Know what you’re
getting into.
Useful answers before
your next offer.
How DSCR loans work: start with the property’s rent.
Understand the ratio, the financing conversation, and what to ask before making an offer.
Read the article ↗02 / THE RENT CHECKThe appraisal number investors can’t afford to overlook: rent.
Why a property can meet the value target and still need a second look at financing.
Read the article ↗03 / GET PREPAREDLess income paperwork. Here’s what you should still have ready.
A simpler personal-income review still calls for an organized loan file.
Read the article ↗04 / INVESTOR PERSPECTIVEA healthy DSCR is a starting point—not a profit forecast.
Put repairs, vacancy, and your exit plan into the conversation, too.
Read the article ↗QUESTIONS WELCOME
Let’s clear
a few things up.
Every property has its own details.
These answers get the conversation started.
What does DSCR stand for?
Debt service coverage ratio. In residential investor lending, it commonly compares qualifying rent with the property’s qualifying housing expense.
Can I use a DSCR loan for a home I’ll live in?
These programs are for investment properties. Discuss owner-occupied financing separately if you intend to live in the home.
Are tax returns or W-2s required?
Generally, DSCR qualification does not rely on traditional personal-income documents. Credit, assets, and property documentation still apply; request the checklist for your program.
Why does the appraiser’s rent estimate matter so much?
When the program uses appraised market rent, a lower accepted rent lowers the ratio at the same payment. That can affect the financing available. The value and rent analyses both deserve attention.
Will you use my lease or the appraiser’s estimated rent?
The selected program determines how lease rent and appraised market rent are reconciled. Share both when available. Do not assume the higher figure will be accepted.
Do I need a 1.25 DSCR?
There is no single minimum for every program. A ratio by itself does not establish approval. Ask for a review of the full scenario.
Can a first-time investor qualify?
There may be options. Investor experience requirements and property eligibility vary by program.
What about an LLC or a short-term rental?
Ask before selecting the loan. Entity borrowing and short-term rental income methods depend on the program; an online revenue projection alone is not a qualification decision.
How much money do I need to put down?
The amount depends on the property, credit, loan structure, and applicable requirements. Plan for closing costs and any required reserves as well as the down payment.
Where does “Let’s review my deal” take me?
To Erika’s CrossCountry Mortgage short contact form. To start a mortgage application, use Apply Now. To choose a time to talk, use Book a conversation.
BRING THE PROPERTY. BRING THE QUESTIONS.
Let’s take a closer look
at your next investment.
A property address, estimated rent, and your goals are a good place to start.
Information checked October 21, 2026. Requirements vary by program. References to other lenders or appraisal forms explain industry practices; they do not establish CCM eligibility.